

A structure permanently attached to the ground is one whose loads are transferred to the soil through its technical framework, i.e. foundations. Whether a holiday cabin is permanently attached to the ground depends on the applicable law.
An object that is not permanently connected to the ground is not considered a building and should be classified as a temporary building. Because a permanently attached building is one that cannot be detached from the ground without damaging its structure, a holiday cabin may, but does not have to, be permanently attached to the ground.
Is a holiday cabin permanently attached to the ground only through foundations?
In administrative case law, permanent attachment of a building to the ground means placing the building so firmly as to ensure its stability and resistance to external factors that could cause it to shift or move to another place. The existence of foundations, however, is not the sole criterion for qualifying a building as permanently attached to the ground. The building is also permanently attached to the ground when it resists the natural forces of nature.
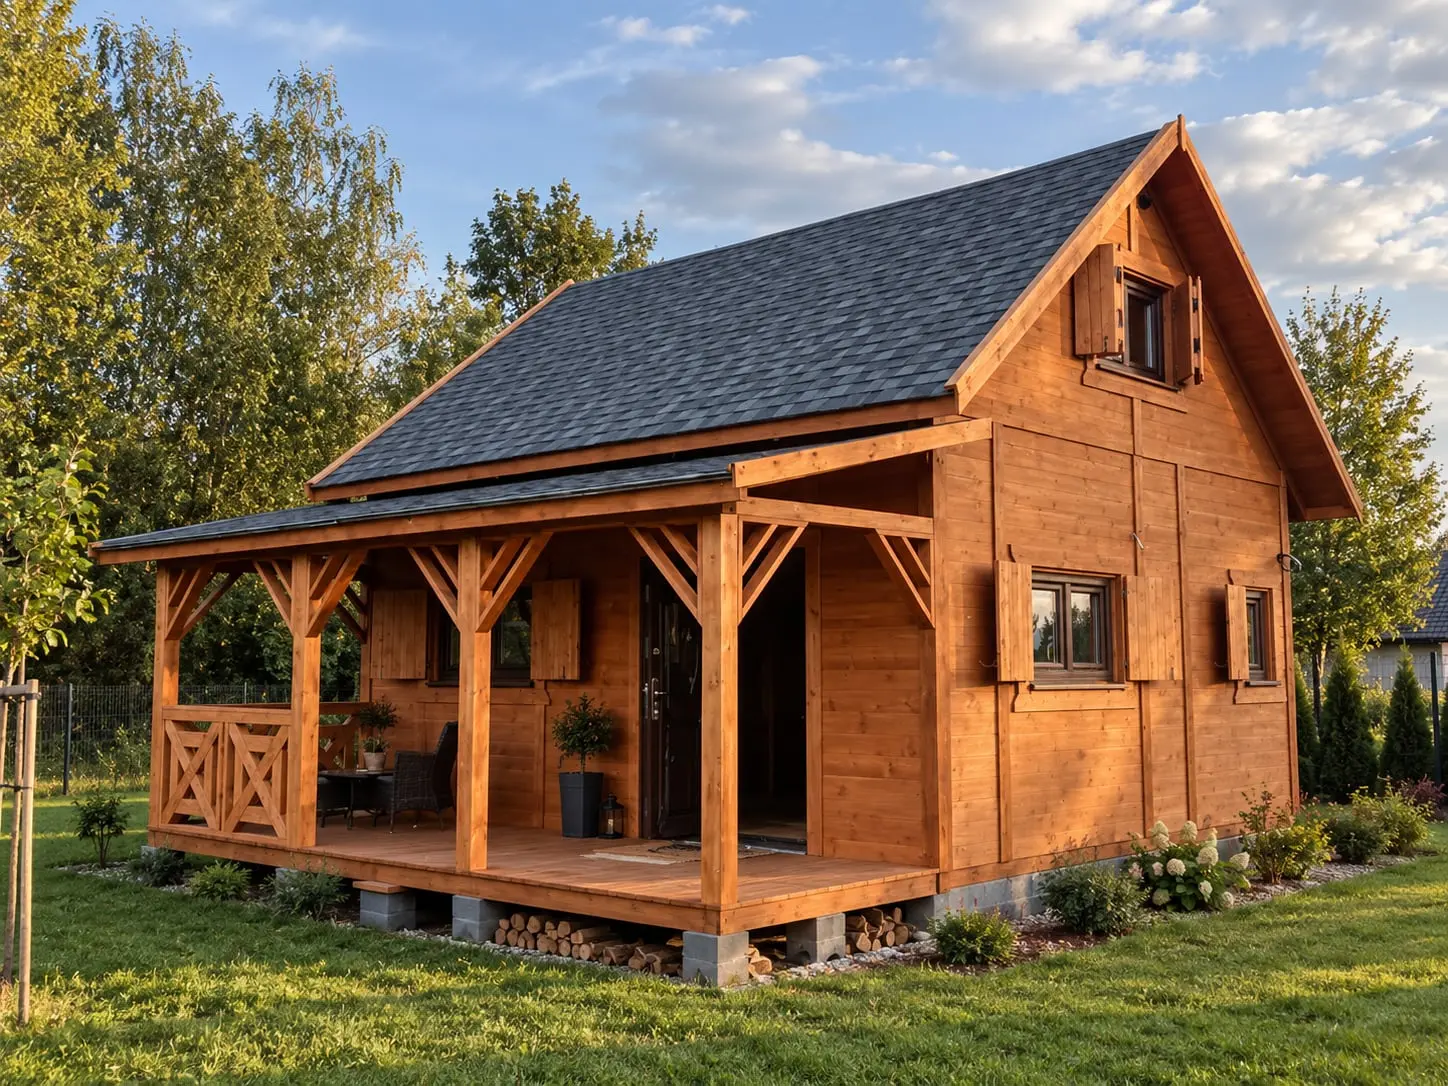
Julian Cabin - 6x7,5m (SSZ)
Miłosz Cabin - 54 m² (CRA)
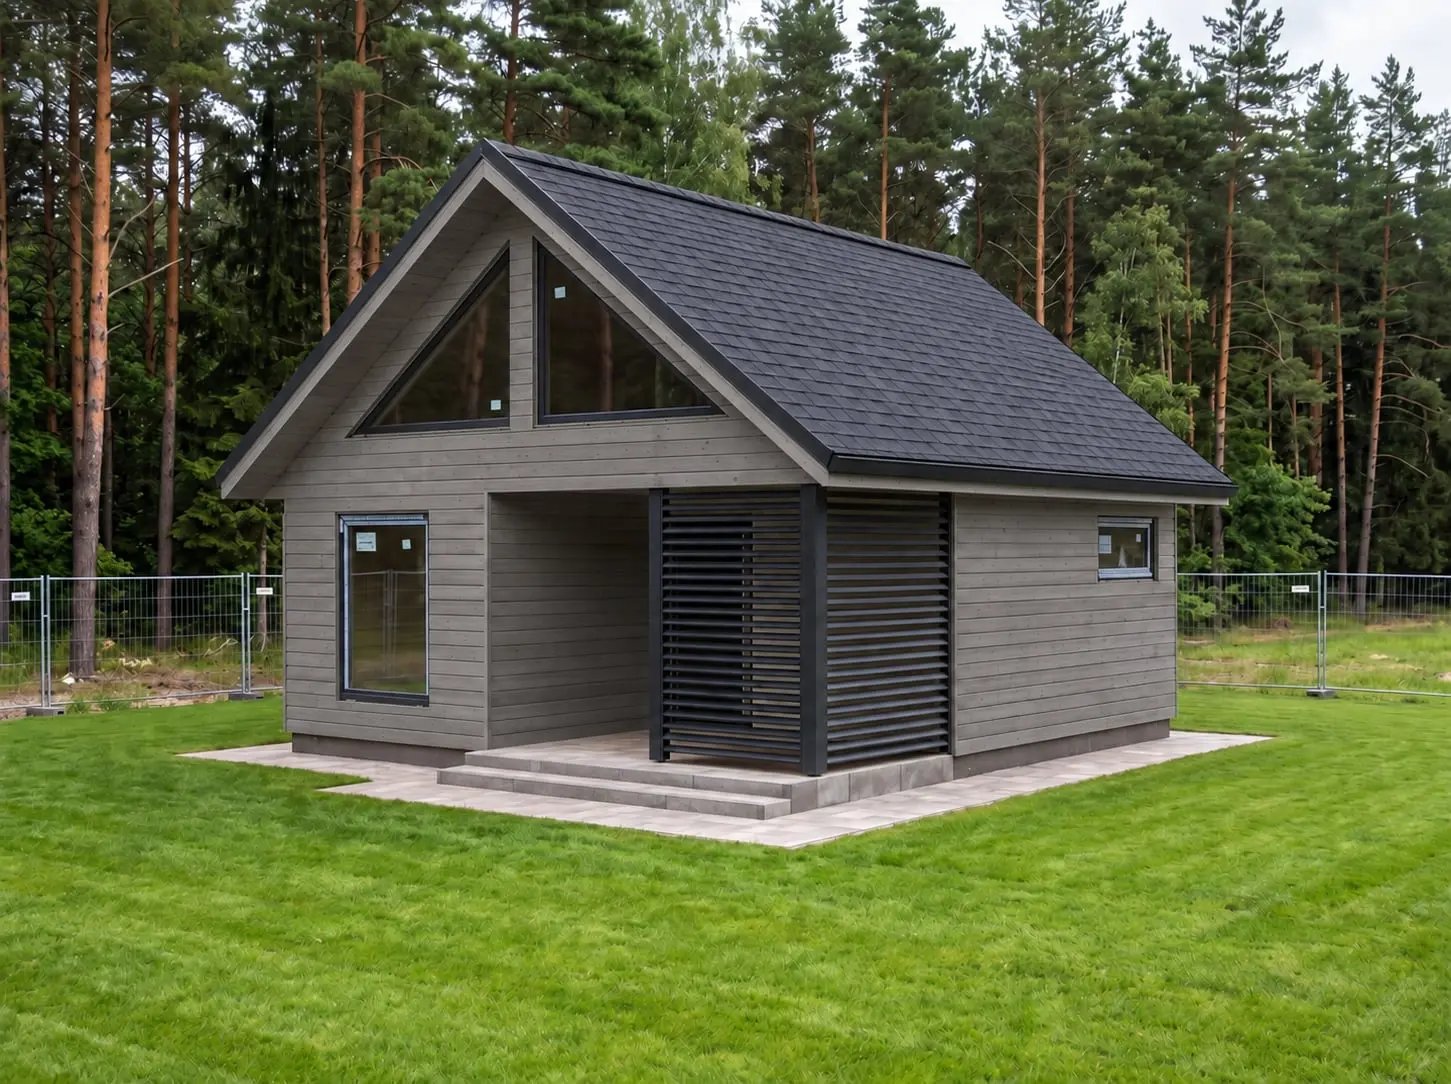
Wiktor IV v2 Cabin - 35 m² (CRA)
When is a holiday cabin a temporary object?
Holiday cabin may be considered a temporary building when it is intended for temporary use for a period shorter than its technical durability. It is also regarded as a temporary object if the cabin is planned for demolition or relocation to another place.
Temporary buildings: notification or permit?
Article 29, paragraph 1(12) of the Building Law Act states that temporary buildings require only a notification to the competent architectural and building administration authority. You should therefore submit the notification to the county office or the city with county rights. For a notification, a construction project for the holiday cabin is not required, nor a decision on the conditions of development.
To avoid building a permit, a holiday cabin must be a free-standing building, i.e. not connected to another building and not utilizing any elements of another structure in its construction. A recreational cabin must also not exceed a floor area of 70m2 and be a ground-floor building (gazebos, greenhouses and sheds do not count toward the built-up area). The number of such objects must not exceed one building per 500m2 of plot area.
Is a holiday cabin permanently attached to the ground and subject to tax?
Property tax applies to such real estate and buildings as:
- buildings or parts of buildings,
- structures or parts thereof associated with running a business activity,
- land.
To know whether you must pay tax for a holiday cabin, you need to know whether it is classified as a building or a structure. A holiday cabin subject to taxation must be permanently connected to the ground, have foundations, have a roof and be separated from space by building partitions. If the cabin fulfills residential needs, it should be taxed as a residential building under property tax.